The penny has been fading for a while, and now Congress has made it official. On Monday, September 28, the Senate passed the Common Cents Act by voice vote, sending it to President Trump, who is expected to sign it. The bill formally ends penny production after 234 years and sets national rules for something shoppers have already started running into: stores rounding cash totals to the nearest nickel.
If you pay mostly with a card, very little changes for you. If you use cash, even occasionally, it helps to know how the rounding works, who it affects, and what to do with the pennies sitting in a jar on your dresser.
Why the Government Stopped Making Pennies
It comes down to cost. According to the U.S. Mint’s 2024 annual report, making and distributing a single penny cost 3.69 cents, almost four times its face value. When a coin costs more to make than it’s worth, the government loses money on every one it ships out. The St. Louis Fed notes that the Mint produced more than 3 billion pennies in fiscal year 2024 and lost $85.3 million doing it.
The profit (or loss) the government makes on issuing money has a name: seigniorage. Dimes and quarters still make money for the Treasury because they cost less than their face value to produce. Pennies and nickels don’t.
The Mint struck its last circulating penny in Philadelphia on November 12, 2025. The new law puts a legal stamp on that decision. The Mint estimates that stopping penny production saves about $56 million a year.
How Nickel Rounding Works
The Common Cents Act lets merchants, banks, and credit unions round cash transactions to the nearest five cents when exact change isn’t available. The rule is symmetrical, and it’s applied to your final total after tax, not to each item.
If your total ends in 1, 2, 6, or 7 cents, it rounds down. A $4.12 total becomes $4.10, and $4.17 becomes $4.15.
If your total ends in 3, 4, 8, or 9 cents, it rounds up. A $4.13 total becomes $4.15, and $4.19 becomes $4.20.
Totals ending in 0 or 5 don’t change. And one small exception: a total of just 1 or 2 cents rounds up to 5 cents so the purchase doesn’t round down to nothing.
The key detail is that this applies only to cash. According to the ABA Banking Journal, the bill makes clear that checks, credit cards, and other noncash payments are not subject to rounding. The same goes for debit cards, electronic transfers, gift cards, and money orders. If you tap your card, you pay $4.13 to the penny.
Does Rounding Cost Shoppers Money?
In theory, rounding should even out. If the last digit of your total were random, you’d round down just as often as you’d round up.
In practice, it’s not quite random. Economists at the Richmond Fed looked at real cash purchases from the Fed’s 2023 Diary of Consumer Payment Choice and found that transactions were somewhat more likely to end in 3, 4, 8, or 9 cents, the digits that round up. Scaled to the whole U.S. adult population, they estimated this “rounding tax” at about $6.06 million a year.
That sounds like a lot until you divide it out. With roughly 258 million adults, it works out to a couple of pennies per person per year. You won’t notice it. Studies from other countries back that up: a Canadian study of grocery purchases after Canada dropped its penny found a small transfer to stores, while a 2007 U.S. study of convenience store data found rounding slightly favored shoppers.
The bigger reason the effect stays small is that most people don’t pay cash much anymore. A 2025 Federal Reserve study found cash made up just 14% of transactions in 2024. Older adults leaned on it more (19% of transactions for people 55 and up) than younger ones (10% for ages 18 to 24).
What About the Nickel?
There’s an irony in all this. Getting rid of the penny will likely increase demand for nickels, and nickels are even more expensive to make. The Mint’s 2024 figures put the cost of a nickel at 13.8 cents, nearly three times its face value.
The Common Cents Act deals with that in two ways. It lets the Treasury explore a cheaper metal mix for the nickel, including an inner layer of zinc instead of the current copper and nickel blend. And the Senate added a requirement that the Treasury give Congress 60 days’ notice before discontinuing any circulating coin.
That second part matters because the Richmond Fed ran the numbers on losing the nickel too. If stores had to round to the nearest dime, the estimated cost to consumers jumps to about $56 million a year, more than nine times the penny-only rounding cost. So don’t expect the nickel to disappear quietly.
Your Pennies Are Still Money
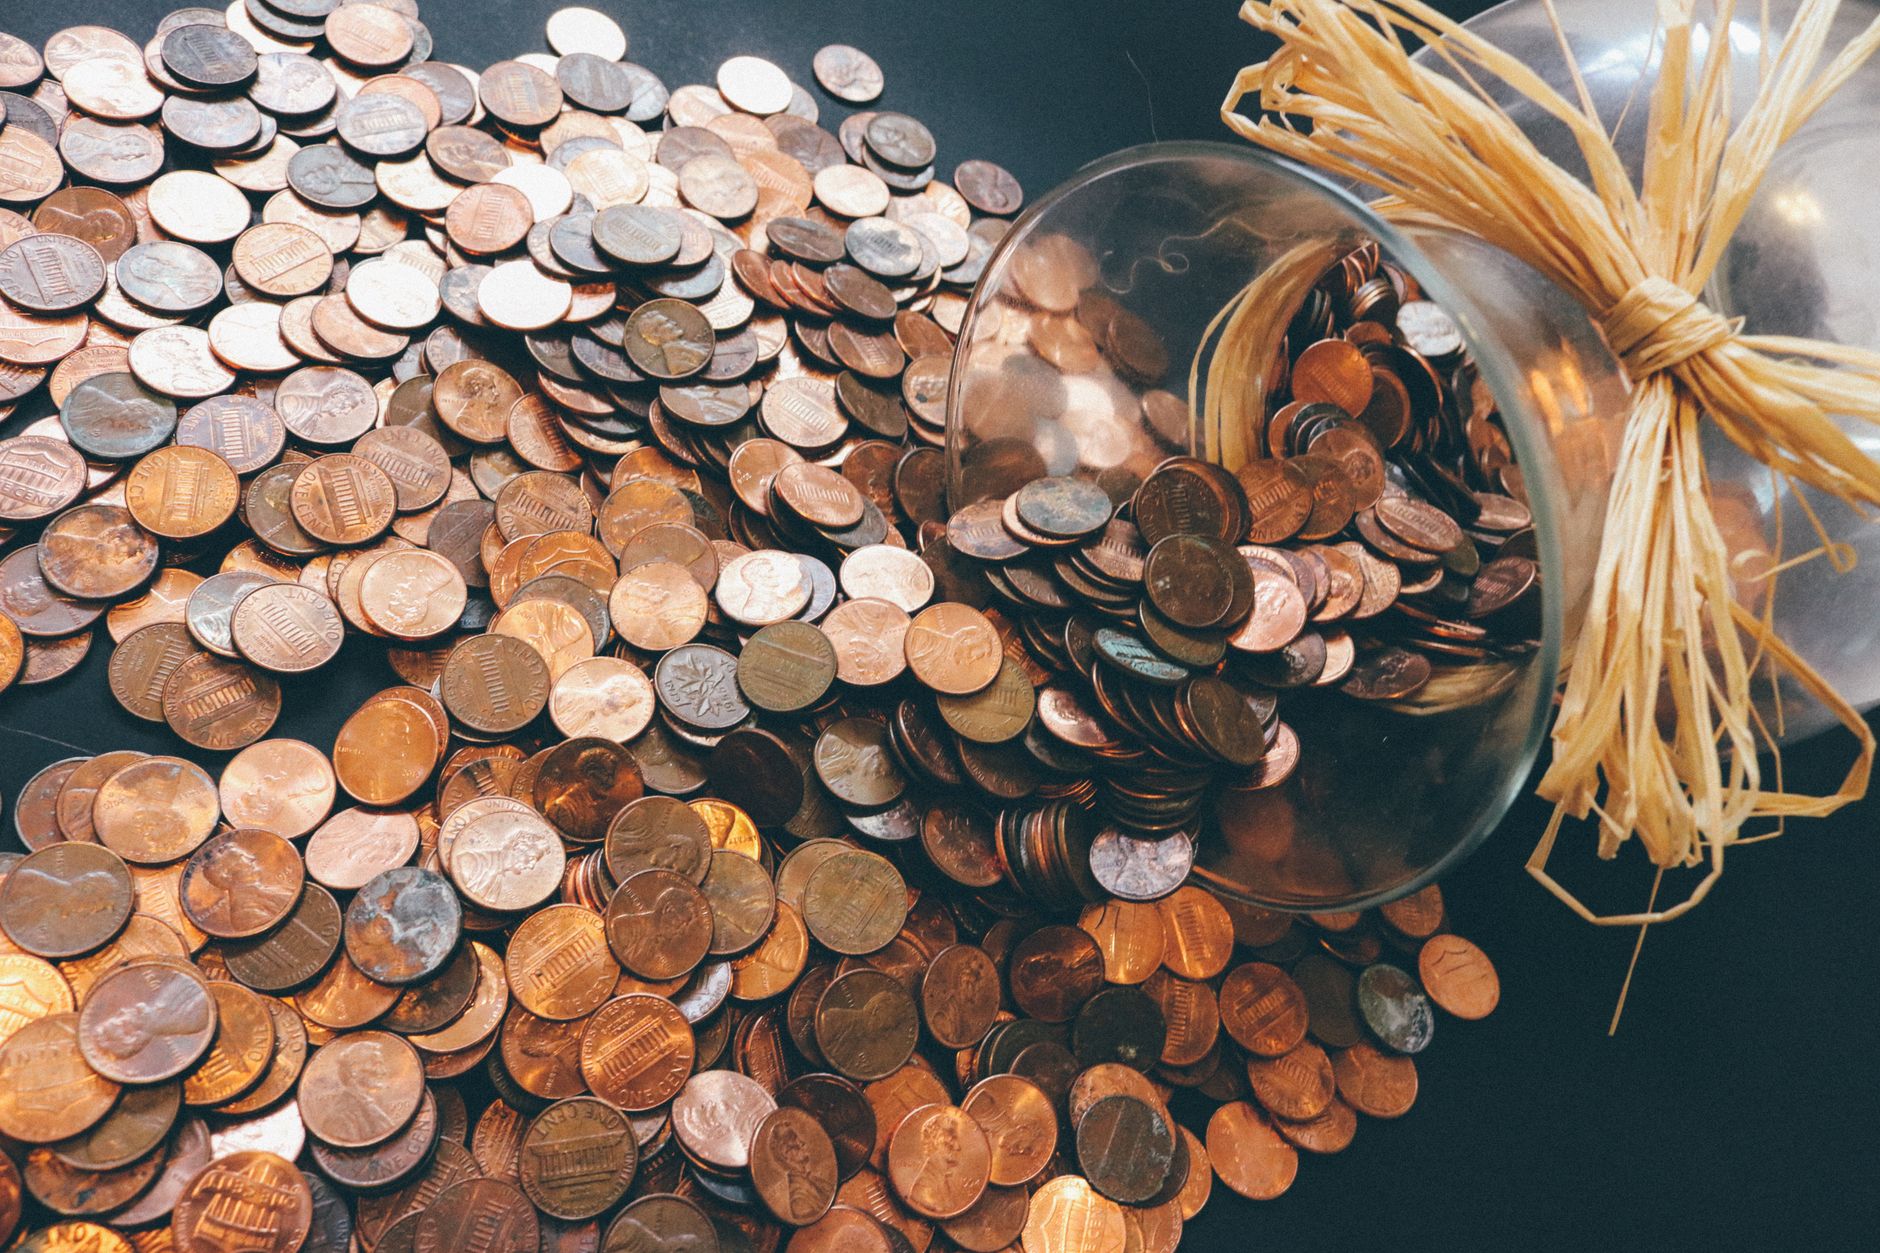
Ending production doesn’t make pennies worthless. They remain legal tender, and you can keep spending them. The St. Louis Fed notes that by some counts there are around 300 billion pennies still in circulation, and the Treasury has encouraged people to spend them to give retailers time to adjust.
If you’ve got a jar full of them, you have a few options. You can spend them at stores that still accept them, which most do. You can roll them and deposit them at your bank or credit union, many of which accept rolled coins for free from account holders. Some banks and credit unions also have free coin counting machines for customers. Retail coin kiosks work too, but they usually take a cut unless you choose a gift card, so read the fee screen before you pour.
Depositing is the smartest move for most people. A jar of a few thousand pennies is only $20 or $30, but sitting in a high-yield savings account it at least earns interest, and it’s one less thing cluttering a shelf.
What This Means Day to Day
For card users, basically nothing changes. Your receipts will still show exact totals.
For cash users, you may see totals rounded at the register, and the effect will be tiny and roughly balanced over time. If you pay cash and want exact change, you can still hand over pennies, and a store can take them. If you’d rather avoid rounding altogether on a purchase, paying with a debit card gets you the exact amount.
It’s a small change on paper. It’s also a reminder of how much the way we pay has shifted: the coin that inspired “a penny saved is a penny earned” now costs nearly four cents to make, and most of us rarely touch one.